Most seven-year-olds can name the toy they want, yet few can explain why the money runs out before the month does. A well-run allowance system for kids closes that gap with weekly practice instead of lectures. Saving, choosing, and waiting are habits children only build by repeating them, and a steady allowance supplies the repetitions.
Money talks at the dinner table rarely stick. A child hears that a mortgage costs more than a bike, and the lesson fades by bedtime. Handling real coins every week does what the speech cannot.
Why Kids Need Money Practice Before They Can Count Change
Quick Tips
- Pick one fixed amount per week, matched to age rather than to requests.
- Split every payment into at least two jars, one for spending and one for saving.
- Let children buy one wanted item each month with their own money.
- Review the jars together every Sunday for five minutes.
Financial educators often say children learn money by handling it, not by hearing about it. A decision with a visible consequence sticks. If a child spends the whole amount on day one, the next two weeks of boredom teach more than any talk.
Practice also builds patience. Waiting three weeks to afford a game feels long to a child, and that feeling is the skill itself. Parents who step in to cover the gap remove the lesson before it starts. That rescue costs the child more than it helps.
Three Jars Versus Digital Tracking for Your Family
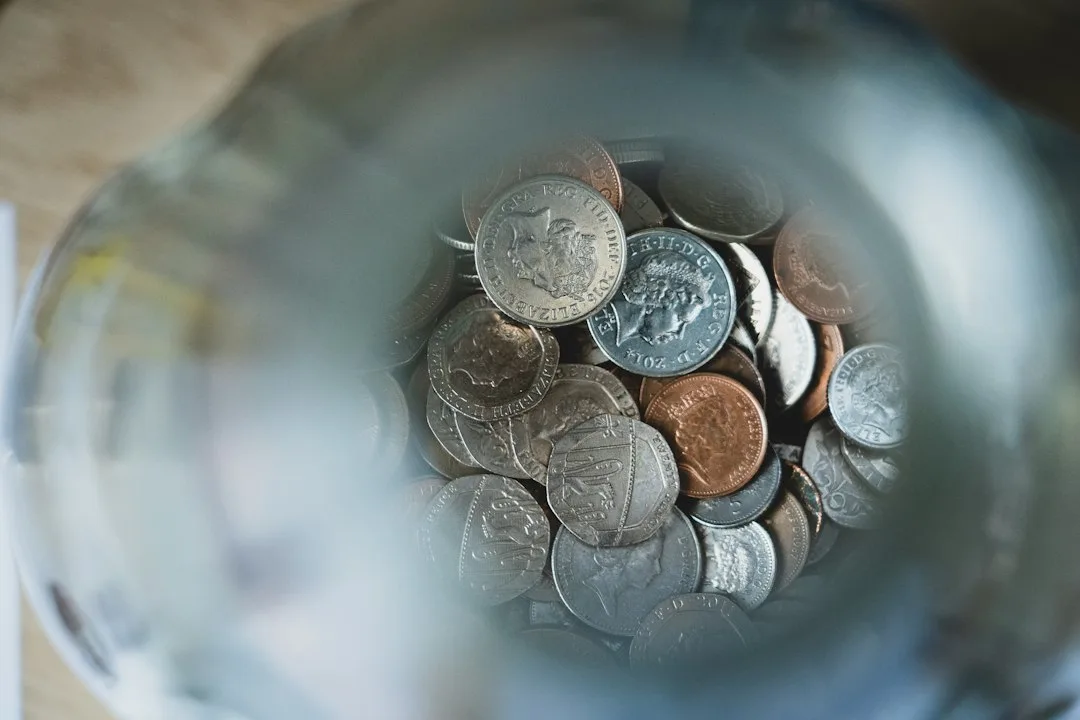
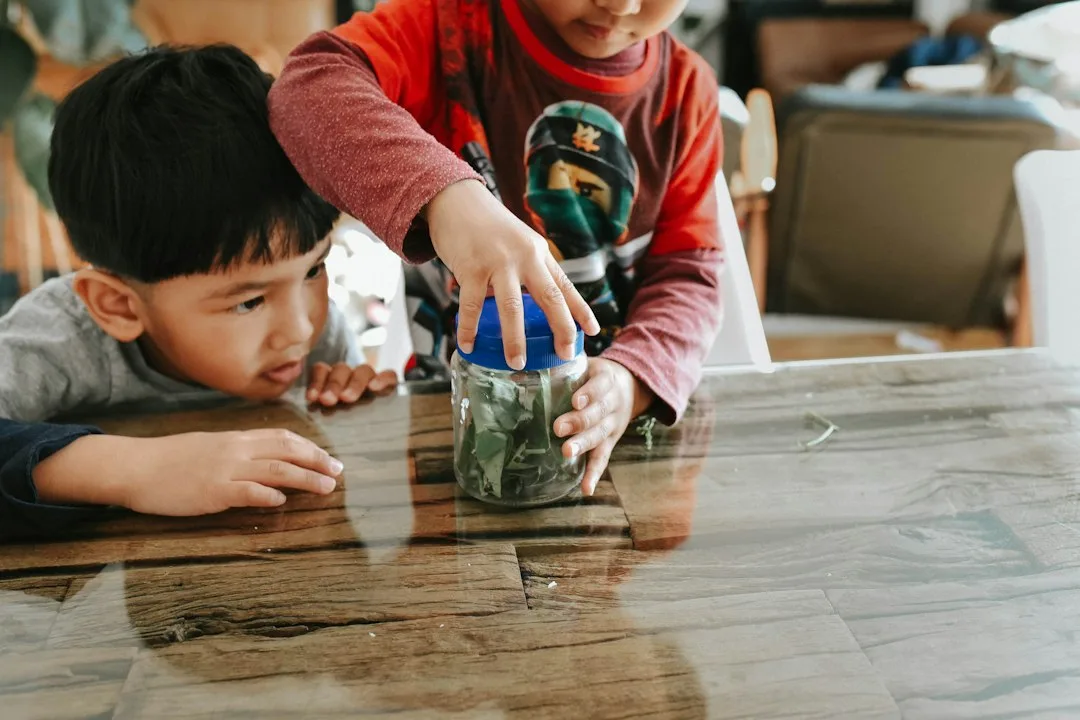
Physical jars remain the cheapest starting point. A set of Ball wide-mouth quart jars with lids gives each child a visible stack of savings. Coins and bills in clear glass show progress in a way an app balance rarely does.
Digital tools suit older kids who already use a phone or tablet. They track chores, schedule payments, and show balances on a screen. The trade-off is that the money feels less real until a card is swiped.
| Method | Best Age Range | Main Trade-Off |
|---|---|---|
| Ball wide-mouth jars | Ages 4 to 8 | Coins can go missing, so count weekly |
| BusyKid app | Elementary and older | Built-in chore tracking with a linked debit card |
| Greenlight card | School age and up | Parent spending controls on each purchase |
| Acorns Early | Older teens | Investing account that carries a small monthly fee |
Setting Up an Allowance System for Kids Step by Step
Start by choosing a fixed weekly amount. Pick a number that fits your budget and your child’s age, then keep it steady for at least a month. A stable figure makes the lesson about planning rather than negotiating.
Next, divide each payment into jars or categories. Spend, save, and give work well for most families, and a fourth category for a planned purchase adds structure. Label each one so the child sees the split without help.
Families in two households can follow the same structure with matching rules at both homes. The approach overlaps with the routines in Why Co-parenting Communication Tools Build Stronger Separated Family Networks, which covers keeping adults aligned. Shared rules stop the child from playing one home against the other.
The Mistake That Undermines Every Payout
The most common error is paying allowance for nothing. Picture a parent who hands over ten dollars every Friday no matter what happened that week. The child learns that money arrives on schedule, so there is nothing to plan for.
Fixing it takes one honest conversation. Tie part of the amount to finished tasks, and let unfinished ones earn nothing. Consistency matters more than the size of the payment.
Tying Pay to Chores Without Turning Home Into a Store
Many parents set a weekly amount for a young child in the range of five dollars, enough for one small treat. That limit does the teaching, because it forces a choice between two wants. Without it, the allowance becomes a bottomless credit line.
Separate allowance from chores every family member does. Making the bed, clearing a plate, and feeding a pet are expected, so they earn nothing. Extra jobs like washing the car or raking leaves can earn a bonus the child chooses to pursue.
Digital Allowance Tools and Screen Time Limits
Digital tools can work well for older children, but they add a screen to a routine that may already involve one. BusyKid and Greenlight both connect payments to a card, which means the child spends from a balance the parent can see. Check whether any app also limits total screen minutes.
Screen time rules deserve their own plan. The approach in Screen Time Limits for Children 2026 — Why Chronometric Parenting Replaces Unrestricted Digital Access offers a model for setting boundaries before a device comes out. Decide those limits first, then add money features on top.
Keeping the Lesson Going as Children Grow
Revisit the system every year or when your child moves to a new school stage. A seven-year-old needs jars, while a twelve-year-old may need a budget sheet and a savings goal. Changing the tools keeps the lesson from feeling childish.
Ask the child to name one thing they would do differently next month. That short reflection turns a payout into a habit. The goal is a young adult who pauses before spending.